
The Levanter Signal. A weekly read of volatility, valuation and the week ahead across crypto, FX and commodities. This is the subscriber tier, and it is free while we build the list. We will tell you before that changes. Subscribe at read.levantermarkets.com.
From the editor. My read, if a friend asked: the storm this week is in energy and the grains, currencies are close to asleep, and crypto’s 17 percent week tells you nothing about which way it goes next.
The seven-day volatility map
This is the part with measurable skill, and it is why it leads the issue. The model tags each market turbulent or calm for the week ahead. In the five-year point-in-time backtest it classified the seven-day regime correctly about 66 percent of the time across 5,118 calls, 95 percent interval 64 to 67, 13 percentage points above its naïve baseline, and 70 percent at thirty days, 17 points above baseline. That is a backtest, not a live forward record: the live scoreboard is only now starting to fill.
Accuracy alone can flatter a model that never commits, so we also score the confidence behind each call. The Brier score is 0.224 against 0.25 for always guessing the base rate, a skill score of 0.104 over 2,559 scored calls. Positive but small. Read the calls as a lean, not a conviction.
For the coming week the model reads 15 markets turbulent: bitcoin, the S&P, silver, oil, copper, natural gas, Brent crude, wheat, corn, soybeans, coffee, sugar, cotton, gasoline and heating oil. The rest of the displayed set is calm, including ether, solana and all seven FX pairs. The average market is therefore contained even though a few names are carrying wide ranges.
Worth naming: 13 of the 15 turbulent markets are commodities, with only bitcoin and the S&P outside that class, and those names sit close to the line. Treat this as turbulence concentrated in one corner of the board rather than a market that is nervous everywhere. The two call for different responses.
Average cross-asset correlation is near 0.38. That is loose enough that markets are still trading their own stories, so spreading risk across them is doing real work.
The full board, market by market
This is the model’s working rather than its conclusion. Volatility is annualised. The median column is each market’s own long-run median, so every row is judged against itself and never against a common threshold: a 6 percent reading in FX can be stretched while a 35 percent reading in crypto is quiet. Percentile is where the current reading sits in that market’s own history. The thirty-day column is there so you can see whether a call is a one-week disturbance or a settled regime.
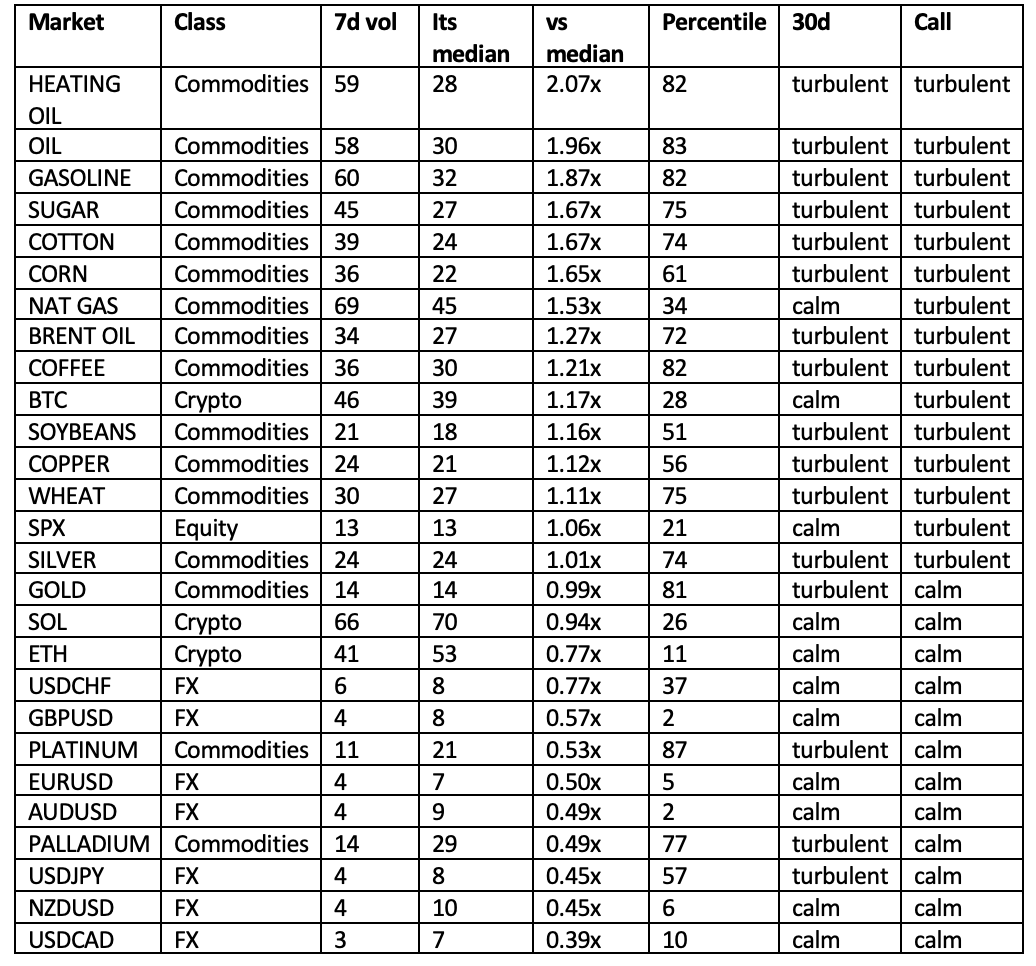
The most stretched reading on the board is heating oil, running 2.07 times its own median, and the quietest is the loonie at 0.39 times. A market can be called turbulent while still sitting below another market’s calm reading, which is the whole point of judging each one against itself.
Treat the rows near the line with less confidence than the rest. The S&P at 1.06x, silver at 1.01x, gold at 0.99x and solana at 0.94x are close enough to their own median that the call could go either way. We would rather flag that than present every row as equally settled. The rows worth acting on are the stretched readings at the top and the quiet ones at the bottom.
Where the two horizons disagree. Turbulent this week but calm at thirty days, natural gas, bitcoin and the S&P. Calm this week but turbulent at thirty days, gold, platinum, palladium and the yen. A split like that flags a near-term move without telling you whether it lasts, so it is the set to watch rather than the set to act on.
Out-of-range flag: sterling is trading outside the volatility range the model was fitted on. The call still prints, but it is an extrapolation and we would discount it accordingly.
The big crypto reads. Bitcoin’s one-week volatility is near 46 percent against a 39 median, 1.18 times its own normal, and ether is near 41 percent against a 53 median, 0.77 times its own normal. Bitcoin reads turbulent at seven days and calm at thirty, and ether reads calm at both seven and thirty days. The two horizons disagree, which flags a near-term move without telling us whether it lasts. In the metals, copper and silver read turbulent at both seven and thirty days, so that is not just a one-week disturbance.
On direction the model is close to a coin flip: 50 percent over 320 backtested crypto calls, a 95 percent interval of 45 to 55 percent that straddles the coin-flip line. We forecast volatility, not direction. Anyone selling you the second thing at these sample sizes is selling you noise.
What this map is not: it says nothing about which way a price goes, it cannot tell you why a market is stretched, and a turbulent call is not a reason to trade. It is a statement about the width of the range, which is the input to position size, not to direction.
What changed since the last Signal
Week on week: Newly turbulent, bitcoin and natural gas. Calmed back to normal, USDJPY, palladium and platinum. Bitcoin is about 8 points richer against its fitted value.
The one chart: bitcoin against its long-run trend
Bitcoin is near 86,000 dollars. The valuation fit models price against how long the network has existed, on a log-log scale. Fair value on that fit lands near 135,000, about 36 percent below the line, and the fitted floor sits near 58,000. Bitcoin has closed above that floor line for roughly 95 percent of the historical sample. That is an in-sample observation, not a tested probability and not a guaranteed level of support.
Our cycle gauge reports a second number, and it is worth being precise about what it is. It fits the same shape of curve, price against network age, but on a different price history and with a different band, then adds halving timing to classify the phase. It reads bitcoin as post-peak cooldown, about 39 percent below its own trend line. Do not read the two figures as confirming each other. They are the same kind of fit run over overlapping data, so close agreement is close to guaranteed and tells you nothing the first number did not. Both are long-horizon context. Where price sits against a multi-year fit says nothing about the next five days, so read it as valuation, not a reason to act on the week.
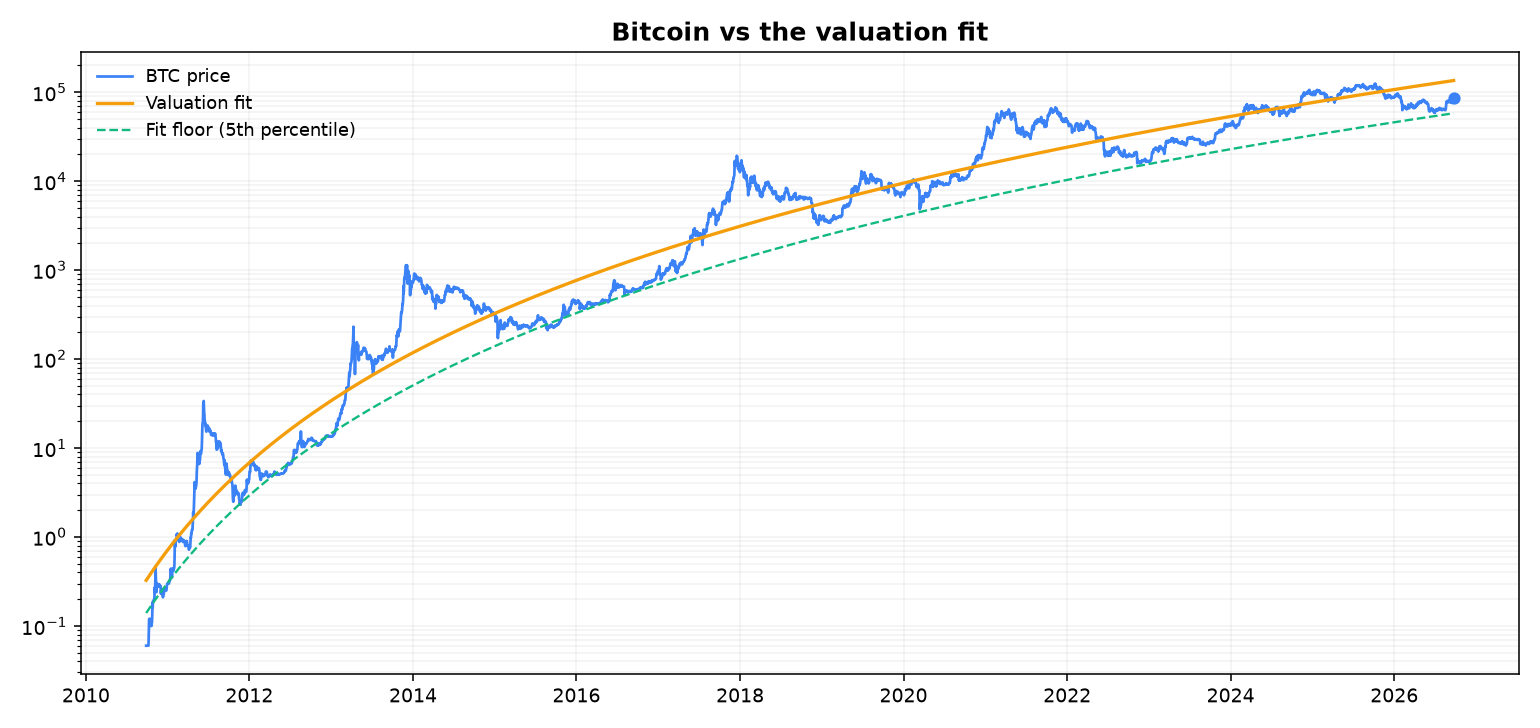
(Chart: bitcoin price against its fitted fair value and floor.)
What the model can and cannot do
It is a statistical fit of price to time. It has no hard economic mechanism behind it, cannot call tops, and may fail outside the historical sample. It is a valuation anchor, not a timing tool. Treat the fair value and the floor as distant reference points, never as targets and never as a reason to size up.
The week behind, and what it rhymes with
Over the past seven days crypto was broad and speculative-led: 35 of 35 coins higher, cap-weighted about +17 percent on the week and +15 percent over thirty days, led by the speculative end, NEAR +88 percent and UNI +71 percent, with a best-to-worst spread near 86 points. Dominance held near 68 percent and the stablecoins we track kept their pegs. In foreign exchange the biggest seven-day move was AUDJPY at +1.7 percent, ranges otherwise tight. In commodities the metals led the week, copper +7 percent, silver +6 percent and platinum +2 percent. The gains were broad, but the largest moves stayed further out on the risk curve, and the dollar and most FX ranges were comparatively quiet.
Read across the three asset classes, the unusual combination is strength in both precious metals and speculative crypto while the dollar remains comparatively quiet. That is consistent with abundant liquidity or a debasement trade, but the tape alone cannot tell us which explanation is driving it.
Subscriber watchlist, with levels
· Bitcoin. Fitted floor near 58,000, fair value near 135,000. A weekly close below the fitted floor would be historically unusual and would challenge the model, rather than automatically creating a buying opportunity.
· Ether volatility. Current annualised volatility is near 41 percent against a historical median around 53. Watch whether the thirty-day classification also flips from calm to turbulent.
· The commodity complex. Whether the turbulent bid broadens beyond silver, oil, copper, natural gas, Brent crude, wheat, corn, soybeans, coffee, sugar, cotton, gasoline and heating oil or fades back to calm.
· Pegs and dominance. Stablecoins are holding and bitcoin dominance is near 68 percent. A tracked peg below 0.995 would trigger Levanter’s wobble alert. A sharp dominance move would show the balance within crypto changing.
To score next week: the model calls bitcoin, the S&P, silver, oil, copper, natural gas, Brent crude, wheat, corn, soybeans, coffee, sugar, cotton, gasoline and heating oil turbulent and the rest calm. In the next issue we score each call the way the model does, whether realised volatility over the week came in above or below the asset’s running-median volatility, and show the hits and misses. That is the claim you can hold this Signal to. Four calls sit close enough to the line that we would not defend them hard: the S&P at 1.06x and silver at 1.01x, called turbulent; gold at 0.99x and solana at 0.94x, called calm. We score them anyway. Quietly dropping the calls that look shaky is how a scoreboard gets flattered, and a scoreboard you cannot trust is worth nothing to you.
*This is the Levanter Signal, the weekly subscriber note, free for now while we build the list. We will tell you before that changes. Subscribe at read.levantermarkets.com.
The daily, weekly and monthly reviews stay free at levantermarkets.com. Educational market analysis, not financial advice.*